Monetary Policy Rates
As on 19 October 2026
| Rate | Current | Effective from |
|---|
| Policy Repo Rate | 5.50% | w.e.f. 7 October 2026 |
| Standing Deposit Facility (SDF) | 5.25% | w.e.f. 7 October 2026 |
| Marginal Standing Facility (MSF) | 5.75% | w.e.f. 7 October 2026 |
| Bank Rate | 5.75% | w.e.f. 7 October 2026 |
| Cash Reserve Ratio (CRR) | 3.00% | fortnight from 29 Nov 2025 |
| Statutory Liquidity Ratio (SLR) | 18.00% | RBI CRR & SLR Directions, 2025 |
Repo, SDF, MSF and Bank Rate checked against the RBI homepage and 7 October MPC resolution.
CRR and SLR checked against the RBI homepage and official reserve-ratio requirements.
Sources: RBI current rates | RBI MPC resolution | RBI CRR change | RBI reserve ratios
Cover Story
Profits reported, with a judgment in the annexure
17 October 2026 | YES Bank, results presentation and disclosure filed with BSE
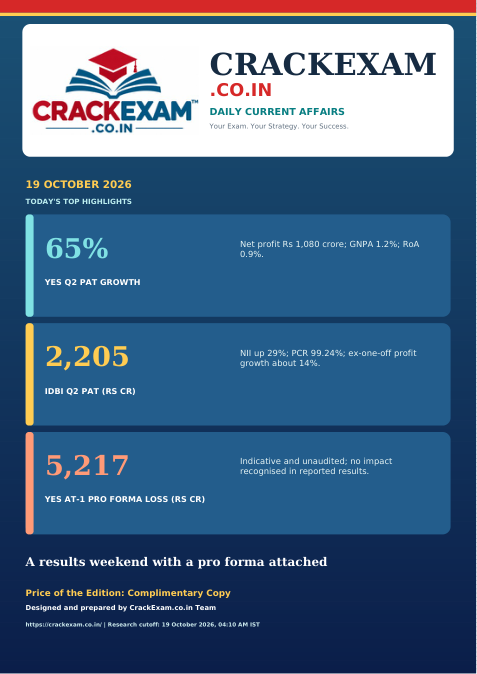
YES Bank's exchange-filed Q2 FY2027 presentation reports net profit of Rs 1,080 crore for the September quarter, up 65% year on year. Operating profit was Rs 1,678 crore, up 29.4%.
Net interest income grew 22.7% year on year to Rs 2,822 crore. Return on assets was 0.9% and return on equity 8.2% for the quarter.
Asset quality improved: Gross NPA ratio stood at 1.2% (1.3% in June 2026 and 1.6% a year earlier) and Net NPA at 0.2%. These are reported results; the presentation separately discloses a pro forma impact of the Supreme Court's AT-1 judgment, covered in the Credit/NPA section.
Key facts- Q2FY27 net profit: Rs 1,080 crore, up 65% year on year
- Operating profit Rs 1,678 crore, up 29.4%; NII Rs 2,822 crore, up 22.7%
- GNPA 1.2%; NNPA 0.2%; RoA 0.9%; RoE 8.2%
Exam takeaway: A reported result and a pro forma disclosure are different statements; check which one a question cites.
Quick revision: YES Q2: net profit Rs 1,080 crore, up 65%.
YES Bank, results presentation and disclosure filed with BSE original sourceRBI & Regulatory Updates
No verified update for this section today.
Banking & Financial Industry News
YES Bank Q2 net profit up 65% to Rs 1,080 crore
17 October 2026 | YES Bank, results presentation and disclosure filed with BSE
YES Bank's exchange-filed Q2 FY2027 presentation reports net profit of Rs 1,080 crore for the September quarter, up 65% year on year. Operating profit was Rs 1,678 crore, up 29.4%.
Net interest income grew 22.7% year on year to Rs 2,822 crore. Return on assets was 0.9% and return on equity 8.2% for the quarter.
Asset quality improved: Gross NPA ratio stood at 1.2% (1.3% in June 2026 and 1.6% a year earlier) and Net NPA at 0.2%. These are reported results; the presentation separately discloses a pro forma impact of the Supreme Court's AT-1 judgment, covered in the Credit/NPA section.
Key facts- Q2FY27 net profit: Rs 1,080 crore, up 65% year on year
- Operating profit Rs 1,678 crore, up 29.4%; NII Rs 2,822 crore, up 22.7%
- GNPA 1.2%; NNPA 0.2%; RoA 0.9%; RoE 8.2%
Exam takeaway: A reported result and a pro forma disclosure are different statements; check which one a question cites.
Quick revision: YES Q2: net profit Rs 1,080 crore, up 65%.
YES Bank, results presentation and disclosure filed with BSE original sourceBanking & Financial Industry News
IDBI Bank Q2 net profit Rs 2,205 crore; NII up 29%
17 October 2026 | IDBI Bank, results presentation filed with BSE
IDBI Bank's exchange-filed presentation reports Q2 FY2027 net profit of Rs 2,205 crore, up about 4% quarter on quarter. The year-on-year comparison reflects a one-off NSDL-related gain of Rs 1,699 crore in Q2 FY2026; excluding that one-off, profit grew about 14% year on year.
Net interest income rose 29% year on year to Rs 4,228 crore, with net interest margin at 4.11%. Operating profit was Rs 2,893 crore and return on assets 1.83%.
Asset quality: Gross NPA 2.12% and Net NPA 0.17%, with provision coverage ratio at 99.24%. Capital adequacy ratio stood at 27.10%.
Key facts- Q2FY27 net profit: Rs 2,205 crore, up about 4% quarter on quarter
- NII Rs 4,228 crore, up 29%; NIM 4.11%; RoA 1.83%
- GNPA 2.12%; NNPA 0.17%; PCR 99.24%; CRAR 27.10%
Exam takeaway: One-off gains distort a year-on-year base; look for the ex-one-off comparison before calling a profit "down".
Quick revision: IDBI Q2: PAT Rs 2,205 crore; NII up 29%.
IDBI Bank, results presentation filed with BSE original sourceBanking & Financial Industry News
Central Bank of India Q2 net profit up 21.10% to Rs 1,469 crore
17 October 2026 | Central Bank of India, results presentation filed with BSE
Central Bank of India's exchange-filed presentation reports Q2 FY2027 net profit of Rs 1,469 crore, up 21.10% year on year (Rs 1,324 crore in Q2 FY2026) and up 10.95% quarter on quarter (Rs 1,213 crore).
Net interest income for the quarter was Rs 4,146 crore, up 26.29% year on year and 5.93% quarter on quarter. Operating profit stood at Rs 2,268 crore.
Asset quality improved: Gross NPA ratio 2.39% and Net NPA ratio 0.31%.
Key facts- Q2FY27 net profit: Rs 1,469 crore, up 21.10% year on year
- NII: Rs 4,146 crore, up 26.29% year on year
- Operating profit Rs 2,268 crore; GNPA 2.39%; NNPA 0.31%
Exam takeaway: Quarter-on-quarter and year-on-year growth can move in different directions; quote the base with the figure.
Quick revision: Central Bank Q2: PAT Rs 1,469 crore, up 21.10%.
Central Bank of India, results presentation filed with BSE original sourceBanking & Financial Industry News
PNB MD: festive demand may add up to 2 percentage points to Q3 credit growth
18 October 2026 interview | The Hindu BusinessLine interview with PNB MD & CEO Ashok Chandra
Punjab National Bank MD & CEO Ashok Chandra told The Hindu BusinessLine in an interview published on 18 October that festive-season demand is likely to add up to 2 percentage points to credit growth in the ongoing quarter. This is management guidance, not an achieved growth figure.
He said the bank has deployed its entire FCNR(B) deposit base to pay down high-cost bulk deposits and certificates of deposit, a liability-side move aimed at improving net interest margins.
The statements describe the bank's expectations and balance-sheet management for the quarter; actual credit growth will be known from subsequent data.
Key facts- Credit-growth addition guided: up to 2 percentage points this quarter (management view)
- FCNR(B) deposits deployed to repay high-cost bulk deposits and CDs
- Source: attributed interview, not an audited result
Exam takeaway: Guidance, deployment of deposits and reported growth are three different things; attribute each to its source.
Quick revision: PNB MD: up to 2 pp festive credit-growth addition guided.
The Hindu BusinessLine interview with PNB MD & CEO Ashok Chandra original sourceEconomy & Financial Awareness
Banks assess income impact of IRDAI's proposed insurance commission caps
18 October 2026 report | Business Standard report on banks' responses to the IRDAI proposal
Business Standard reported on 18 October that banks are assessing the fee-income impact of IRDAI's proposed caps on insurance commissions, including expense-of-management limits and product- and channel-specific commission caps. The measures are at the proposal stage, not final rules.
Per the report, RBL Bank estimates its bancassurance income could decline 50-60%, while Canara Bank sees an impact of up to Rs 200 crore (of which Rs 120-145 crore relates to life insurance).
IIFL Capital estimates bancassurance accounts for about 10% of banks' fee income and about 3% of profit after tax. These are analyst and bank estimates carried in the report, attributed here as such.
Key facts- IRDAI commission caps: proposed, not final (report)
- RBL Bank estimate: 50-60% decline in bancassurance income (report)
- IIFL Capital: bancassurance about 10% of fee income, about 3% of PAT (report)
Exam takeaway: A regulator's proposal, a bank's estimate and a final rule are at different stages; do not treat a reported impact estimate as an effected change.
Quick revision: IRDAI caps: proposal stage; banks assessing impact.
Business Standard report on banks' responses to the IRDAI proposal original sourceGovernment Schemes
No verified update for this section today.
Credit/NPA & Risk Management
YES Bank: AT-1 judgment would have turned Q2 profit into Rs 5,217 crore loss (pro forma)
Presentation dated 17 October 2026 | YES Bank, Q2 FY2027 investor presentation filed with BSE
YES Bank's Q2 presentation states that the Supreme Court, by its judgment dated 15 October 2026, upheld the Bombay High Court judgment relating to the write-down of the bank's AT-1 bonds aggregating Rs 8,415 crore and dismissed the appeals. The bank says it is evaluating consequential actions, implementation requirements, financial and regulatory implications and legal remedies.
Pending completion of that assessment and the appropriate accounting treatment, no impact of the judgment has been recognised in the reported Q2 FY2027 results.
For transparency, the presentation gives indicative, unaudited pro forma figures assuming the estimated impact as at 30 September 2026: net profit of Rs 1,080 crore becomes a loss of Rs 5,217 crore; CET-1 falls to 11.4% from 13.7%; RoA becomes -4.3% against 0.9%. The bank flags the pro forma estimates as subject to revision. The Economic Times reported on 18 October that, on the same basis, the half-year profit of Rs 2,151 crore would become a loss of Rs 4,146 crore, citing the presentation.
Key facts- Reported Q2: profit Rs 1,080 crore; pro forma: loss of Rs 5,217 crore
- Pro forma CET-1 11.4% vs 13.7% reported; RoA -4.3% vs 0.9%
- No judgment impact recognised in reported results; assessment ongoing
Exam takeaway: A pro forma table answers "what if the impact were recognised now"; it is not the reported result and is subject to revision.
Quick revision: YES AT-1 pro forma: Q2 loss of Rs 5,217 crore.
YES Bank, Q2 FY2027 investor presentation filed with BSE original source The Economic Times, 18 October 2026National, International & Appointments
Week's BFSI appointments: IL&FS CMD, Federal Bank ED, Barclays India legal head
Week roundup reported 18 October 2026 | Economic Times BFSI leadership roundup of 18 October 2026
The Economic Times BFSI roundup of 18 October reports that the Ministry of Corporate Affairs designated Nagaraju Maddirala as Chairman and Managing Director of IL&FS for two years; he had been appointed to the IL&FS board by an NCLT order of 1 October. He follows Nand Kishore, whose tenure ended on 30 September.
Federal Bank elevated Virat Sunil Diwanji as Executive Director for three years after RBI approval; he took charge as Additional Executive Director on 12 October, per the report.
Barclays India appointed Sonali Sharma as Managing Director and Head of Legal, per the same roundup. Appointment items in this roundup are dated across the week and are carried here with their dates and attribution.
Key facts- IL&FS CMD: Nagaraju Maddirala, designated for 2 years (MCA; report)
- Federal Bank ED: Virat Sunil Diwanji, 3-year term after RBI approval (report)
- Barclays India MD & Head of Legal: Sonali Sharma (report)
Exam takeaway: Designation, regulatory approval and the date of taking charge are separate steps; appointment roundups mix all three.
Quick revision: Appointments: IL&FS CMD, Federal Bank ED named.
Economic Times BFSI leadership roundup of 18 October 2026 original sourceKnowledge Article
Reported results versus pro forma disclosure
YES Bank Q2 FY2027 investor presentation, 17 October 2026
Reported results are the audited-or-reviewed figures a bank recognises in its accounts for the period. They are what "profit up 65%" refers to. A bank may not recognise an event's impact while its assessment and accounting treatment are still being determined.
A pro forma disclosure answers a what-if question: what would key figures look like if a specific impact were recognised on a stated date? YES Bank's presentation labels its table "indicative and unaudited" and assumes the estimated impact as at 30 September 2026; the same reported profit of Rs 1,080 crore becomes a pro forma loss of Rs 5,217 crore.
Pro forma figures are subject to revision and do not change the reported result. CET-1 of 11.4% on the pro forma basis does not mean the bank's reported CET-1 of 13.7% is wrong; they answer different questions.
In the exam, read the stem for "reported", "pro forma", "estimated" and "as at" dates, and match the figure to the basis being asked about.
Key facts- Reported: what is recognised in the accounts for the period
- Pro forma: a what-if on a stated basis, indicative and subject to revision
- Match every figure in an answer to its basis and date
YES Bank Q2 FY2027 investor presentation, 17 October 2026 original sourcePractical Banking Case Study
Building a pro forma figure from an assumed impact
Illustrative study, not news. Balances below are assumed; method checked on 19 October 2026.
Assume a bank reports a quarterly net profit of Rs 800 crore. A court judgment could require recognising an impact estimated at Rs 6,000 crore as at the quarter end. The bank recognises nothing yet and discloses an indicative pro forma.
Working- Reported net profit: Rs 800 crore (recognised in the accounts).
- Pro forma profit = reported profit minus assumed impact = Rs 800 - Rs 6,000 = a loss of Rs 5,200 crore.
- If CET-1 capital falls by the same Rs 6,000 crore against risk-weighted assets of, say, Rs 1,00,000 crore, the CET-1 ratio drops by 6 percentage points; 13% reported becomes about 7% pro forma.
- The reported ratio stays 13% until recognition; only the pro forma line moves.
Exam takeaway: Compute the pro forma by applying the assumed impact to the reported figure, and never quote the pro forma as the reported result.
Today's Scheme
Stand-Up India Scheme (SUPI): features and current status
Department of Financial Services, Ministry of Finance
Launched on 5 April 2016, Stand-Up India promotes entrepreneurship among Scheduled Castes, Scheduled Tribes and women. It offers a composite loan between Rs 10 lakh and Rs 1 crore to entrepreneurs above 18 years of age, through scheduled commercial banks.
Loans fund greenfield projects in manufacturing, services or trading, and activities allied to agriculture. Repayment runs up to seven years including a moratorium of 18 months. Margin money of up to 15% may come through convergence with eligible central or state schemes, but the borrower must bring in at least 10% of the project cost.
Applications route through the www.standupmitra.in portal, which also provides guidance from training to loan application, or through www.jansamarth.in. As on 28 February 2025, 2.67 lakh accounts had been sanctioned Rs 60,504 crore, of which Rs 34,450 crore was disbursed; women accounted for 1.99 lakh accounts.
Current status per the DFS page: the scheme ran up to 31 March 2025, in line with the 15th Finance Commission. The Budget for FY 2025-26 announced a new scheme for 5 lakh women, SC and ST first-time entrepreneurs, providing term loans up to Rs 2 crore over the next five years and incorporating lessons from Stand-Up India; the EFC note is under preparation, so the successor is announced but not yet launched.
Key facts- Loan: Rs 10 lakh to Rs 1 crore composite, via SCBs; age 18+; SC/ST and women entrepreneurs
- Greenfield manufacturing/services/trading; repayment up to 7 years with 18-month moratorium; minimum 10% own contribution
- Status: scheme ran up to 31.03.2025; successor (Rs 2 crore loans, 5 lakh first-time entrepreneurs) announced in Budget FY 2025-26, not yet launched
Exam takeaway: Separate what exists from what is announced: Stand-Up India's Rs 10 lakh-1 crore window, its 31.03.2025 end, and the successor's Rs 2 crore limit and 5-lakh target are each distinct facts.
Department of Financial Services, Ministry of Finance original sourceBank Promotion Exam Corner
Policy rates unchanged from the 18 October edition: repo 5.50%, SDF 5.25%, MSF/Bank Rate 5.75%, effective 7 October; CRR 3%; SLR 18%.
Q2FY27 net profit: YES Bank Rs 1,080 crore (up 65%), IDBI Bank Rs 2,205 crore (up about 4% QoQ; ex-one-off about 14% YoY), Central Bank of India Rs 1,469 crore (up 21.10% YoY).
YES Bank AT-1: reported Q2 results recognise no judgment impact; the indicative pro forma shows a Rs 5,217 crore loss and CET-1 of 11.4%.
IRDAI insurance commission caps are proposed, not final; bank and analyst impact estimates are reported estimates, not effected changes.
Daily MCQ Challenge
1. Which bank reported the highest Q2 FY2027 net profit among the three in this edition?
A. YES Bank
B. Central Bank of India
C. IDBI Bank
D. Punjab National Bank
Answer: C. IDBI Bank reported Rs 2,205 crore, above YES Bank's Rs 1,080 crore and Central Bank of India's Rs 1,469 crore; PNB gave an interview, not results.
2. YES Bank's pro forma Q2 loss assumes recognition of the estimated impact of:
A. The IRDAI commission caps
B. The Supreme Court judgment on AT-1 bonds
C. The FCNR(B) deployment
D. A one-off NSDL gain
Answer: B. The pro forma assumes the estimated impact, as at 30 September 2026, of the SC judgment upholding the quashing of the Rs 8,415 crore AT-1 write-down.
3. Under the Stand-Up India Scheme, the composite loan range was:
A. Rs 1 lakh to Rs 10 lakh
B. Rs 10 lakh to Rs 1 crore
C. Rs 1 crore to Rs 2 crore
D. Rs 5 lakh to Rs 50 lakh
Answer: B. Stand-Up India offered Rs 10 lakh-Rs 1 crore composite loans via scheduled commercial banks; the announced successor scheme provides term loans up to Rs 2 crore.
4. Per the Business Standard report, IRDAI's proposed insurance commission caps are:
A. Final rules already in force
B. A proposal on which banks are preparing feedback
C. Applicable only to life insurers
D. A Supreme Court direction
Answer: B. The report describes a proposal; RBL Bank's 50-60% and Canara Bank's Rs 200 crore figures are impact estimates, not effects of a final rule.
5. Who was designated Chairman and Managing Director of IL&FS for two years, per the ET BFSI roundup?
A. Virat Sunil Diwanji
B. Sonali Sharma
C. Nagaraju Maddirala
D. Nand Kishore
Answer: C. The MCA designated Nagaraju Maddirala; Nand Kishore is the predecessor whose tenure ended on 30 September.
Revision: recent days
16 October 2026: Earlier edition: September PLFS unemployment 5.0% for persons aged 15+; FERR user-contract threshold strictly above USD 2 million, subject to all scope conditions.
17 October 2026: Earlier edition: RBL amalgamation approval of 16 October is not its 1 December effective date; the Rs 14,614 SGB price is tranche-specific.
18 October 2026: Earlier edition: the finance ministry's minimum-balance statement was a policy rebuttal, not a new regulation; the SC AT-1 judgment date (15 October) differs from the bank disclosure date (16 October).
Sources and publication information
The YES Bank, IDBI Bank and Central Bank of India stories use the banks' own exchange-filed Q2 FY2027 presentations dated 17 October. The YES Bank pro forma figures come from the same presentation; the half-year pro forma comparison is attributed to The Economic Times report of 18 October. The PNB item is an attributed BusinessLine interview (guidance, not results). The IRDAI commission-cap item is an attributed Business Standard report of banks' responses to a proposal, not a final rule. The appointments item is the attributed ET BFSI week roundup of 18 October with each event's date. No new RBI press release appeared after the 16 October batch used earlier, and the two PIB releases dated 18 October (a Punjab anti-drug event announcement and a school e-waste campaign) carry no banking-exam content. Public sources are linked by name, not printed as raw URLs. All questions are original practice.