Monetary Policy Rates
As on 18 October 2026
| Rate | Current | Effective from |
|---|
| Policy Repo Rate | 5.50% | w.e.f. 7 October 2026 |
| Standing Deposit Facility (SDF) | 5.25% | w.e.f. 7 October 2026 |
| Marginal Standing Facility (MSF) | 5.75% | w.e.f. 7 October 2026 |
| Bank Rate | 5.75% | w.e.f. 7 October 2026 |
| Cash Reserve Ratio (CRR) | 3.00% | fortnight from 29 Nov 2025 |
| Statutory Liquidity Ratio (SLR) | 18.00% | RBI CRR & SLR Directions, 2025 |
Repo, SDF, MSF and Bank Rate checked against the RBI homepage and 7 October MPC resolution.
CRR and SLR checked against the RBI homepage and official reserve-ratio requirements.
Sources: RBI current rates | RBI MPC resolution | RBI CRR change | RBI reserve ratios
Cover Story
A results season with the fine print attached
17 October 2026 | HDFC Bank, official Q2 FY2027 earnings presentation
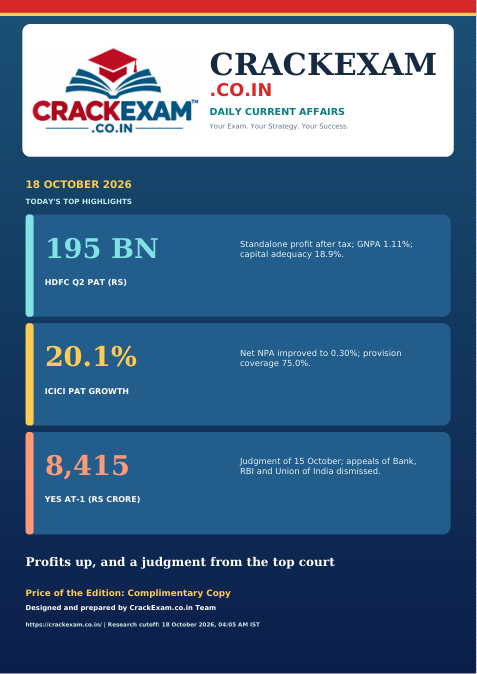
HDFC Bank announced its September-quarter (Q2 FY2027) results on 17 October 2026. The official presentation reports standalone profit after tax of Rs 195 billion (about Rs 19,500 crore) for the quarter, with standalone EPS of Rs 12.7.
Gross NPA ratio stood at 1.11% (0.87% excluding agriculture). Net interest margin was 3.16% on total assets, return on assets 1.78%, and the capital adequacy ratio 18.9% with CET1 at 17.1%.
Average deposits rose 16.8% year on year to Rs 31,664 billion, and average gross advances grew 16.2% year on year. Average CASA deposits grew 1.5% quarter on quarter. Growth rates describe averages for the quarter, not single-day balances.
Key facts- Standalone Q2 PAT: Rs 195 billion; EPS Rs 12.7
- GNPA 1.11%; NIM 3.16%; RoA 1.78%
- Capital adequacy 18.9%, of which CET1 17.1%
Exam takeaway: Profit, asset-quality and capital ratios measure different things; do not read a profit rise as proof of a GNPA change.
Quick revision: HDFC Q2: PAT Rs 195 bn; GNPA 1.11%.
HDFC Bank, official Q2 FY2027 earnings presentation original sourceRBI & Regulatory Updates
No verified update for this section today.
Banking & Financial Industry News
HDFC Bank reports Rs 195 billion Q2 profit; GNPA 1.11%
17 October 2026 | HDFC Bank, official Q2 FY2027 earnings presentation
HDFC Bank announced its September-quarter (Q2 FY2027) results on 17 October 2026. The official presentation reports standalone profit after tax of Rs 195 billion (about Rs 19,500 crore) for the quarter, with standalone EPS of Rs 12.7.
Gross NPA ratio stood at 1.11% (0.87% excluding agriculture). Net interest margin was 3.16% on total assets, return on assets 1.78%, and the capital adequacy ratio 18.9% with CET1 at 17.1%.
Average deposits rose 16.8% year on year to Rs 31,664 billion, and average gross advances grew 16.2% year on year. Average CASA deposits grew 1.5% quarter on quarter. Growth rates describe averages for the quarter, not single-day balances.
Key facts- Standalone Q2 PAT: Rs 195 billion; EPS Rs 12.7
- GNPA 1.11%; NIM 3.16%; RoA 1.78%
- Capital adequacy 18.9%, of which CET1 17.1%
Exam takeaway: Profit, asset-quality and capital ratios measure different things; do not read a profit rise as proof of a GNPA change.
Quick revision: HDFC Q2: PAT Rs 195 bn; GNPA 1.11%.
HDFC Bank, official Q2 FY2027 earnings presentation original sourceBanking & Financial Industry News
ICICI Bank Q2 profit rises 20.1% to Rs 148.43 billion
17 October 2026 | ICICI Bank, results press release filed with BSE
ICICI Bank's exchange-filed release reports profit after tax of Rs 148.43 billion (about Rs 14,843 crore) in Q2-2027, up 20.1% year on year. Core operating profit grew 21.8% to Rs 208.05 billion.
Net interest income for the quarter grew 17.7% year on year to Rs 497.23 billion. Net NPA ratio was 0.30% at 30 September 2026, down from 0.35% at 30 June 2026. Gross NPA ratio improved to 1.20% from 1.58% a year earlier.
Provision coverage ratio was 75.0% at 30 September 2026 (74.7% at 30 June 2026). Common Equity Tier 1 ratio was 16.01% and total capital adequacy ratio 16.68%. Net additions to gross NPAs were Rs 12.13 billion, below Rs 13.86 billion a year earlier.
Key facts- Q2-2027 PAT: Rs 148.43 billion, up 20.1% year on year
- NII: Rs 497.23 billion, up 17.7%
- Net NPA 0.30%; provision coverage 75.0%; CET1 16.01%
Exam takeaway: Gross additions, net additions and write-offs are separate lines in an NPA movement table; a lower net addition is not a lower stock of NPAs.
Quick revision: ICICI Q2: PAT up 20.1%; net NPA 0.30%.
ICICI Bank, results press release filed with BSE original sourceBanking & Financial Industry News
Axis Bank Q2 net profit up 38% to Rs 7,003 crore
17 October 2026 | Axis Bank, official results press release
Axis Bank's official release reports Q2FY27 net profit of Rs 7,003 crore, up 38% year on year. Net interest income stood at Rs 15,371 crore, up 12% year on year and 5% quarter on quarter, with net interest margin at 3.36%.
Core operating profit was Rs 10,998 crore, up 11% year on year, while operating cost grew 9%. The release attributes the profit growth partly to lower provisions.
As on 30 September 2026, reported Gross NPA was 1.16% and Net NPA 0.35%. Provision coverage, as a proportion of Gross NPAs, stood at 70%.
Key facts- Q2FY27 net profit: Rs 7,003 crore, up 38% year on year
- NII: Rs 15,371 crore, up 12%; NIM 3.36%
- GNPA 1.16%; NNPA 0.35%; provision coverage 70%
Exam takeaway: Compare each bank's ratios only with its own prior periods unless definitions and bases are identical.
Quick revision: Axis Q2: net profit Rs 7,003 crore; GNPA 1.16%.
Axis Bank, official results press release original sourceBanking & Financial Industry News
Punjab & Sind Bank Q2 net profit up about 40% to Rs 412 crore
17 October 2026 | Punjab & Sind Bank, results presentation filed with BSE
Punjab & Sind Bank's exchange-filed presentation reports September-quarter net profit of Rs 412 crore, up 39.66% year on year. Operating profit was Rs 618 crore, up 22.38%.
Net interest income rose 22.32% year on year to Rs 1,162 crore, with net interest margin at 2.77%, up 17 basis points. Core fee income was Rs 246 crore, up 23.62%.
Asset quality improved: Gross NPA 2.09%, Net NPA 0.61%, provision coverage ratio (with technical write-offs) 92.48%, and slippage ratio 0.20%.
Key facts- Q2 net profit: Rs 412 crore, up 39.66% year on year
- NII: Rs 1,162 crore, up 22.32%; NIM 2.77%
- GNPA 2.09%; NNPA 0.61%; PCR (with TWO) 92.48%
Exam takeaway: A provision coverage ratio "with technical write-offs" is computed differently from a plain PCR; quote the stated variant.
Quick revision: P&S Bank Q2: net profit Rs 412 crore; NIM 2.77%.
Punjab & Sind Bank, results presentation filed with BSE original sourceBanking & Financial Industry News
Indian Bank raises FY27 advances-growth guidance to 13-14%
17 October 2026 interview; results announced 15 October | NDTV Profit interview with MD & CEO Binod Kumar
In an NDTV Profit interview published on 17 October, Indian Bank MD & CEO Binod Kumar said the bank has raised its FY27 advances-growth guidance to 13-14% and its deposit-growth guidance to 11-12% from 9-11% earlier. Guidance is management's stated expectation, not a result.
The bank's September-quarter results, announced on 15 October, showed net profit up 14.7% year on year to Rs 3,462 crore and net interest income up 18% to Rs 7,719 crore, according to the report. Deposits grew 12.5% year on year; the domestic CASA ratio was 39.36% against 39.73% in June.
Kumar expects credit costs around 0.22-0.23% in coming quarters and aims to complete Rs 3,500 crore of expected-credit-loss provisions by March 2027, having provided about Rs 2,500 crore cumulatively by September. He expects NIM to expand 5-6 basis points following a 25-basis-point repo rate hike.
Key facts- FY27 advances-growth guidance: 13-14% (raised)
- Q2 net profit Rs 3,462 crore, up 14.7%; NII Rs 7,719 crore, up 18%
- ECL provisioning target: Rs 3,500 crore by March 2027
Exam takeaway: Distinguish announced results from forward guidance, and a percentage-point growth target from an interest margin.
Quick revision: Indian Bank: FY27 loan-growth guidance 13-14%.
NDTV Profit interview with MD & CEO Binod Kumar original sourceEconomy & Financial Awareness
Finance ministry: most PSBs waived or reduced minimum-balance charges
16 October 2026 statement; reported 16-17 October | PTI reports of a finance ministry statement (Rediff; The Hindu BusinessLine)
The finance ministry said on 16 October that most public sector banks have either waived or reduced charges for non-maintenance of minimum balances in their regular savings accounts, citing financial-inclusion and customer-centric objectives. PTI carried the statement the same day; The Hindu BusinessLine published it on 17 October.
The statement was a point-by-point rebuttal to Samajwadi Party president Akhilesh Yadav's criticism of banking reforms. It is a policy statement responding to criticism, not a new regulation or directive. No new charge rule takes effect from it, and each bank's own published schedule of charges continues to govern its accounts.
The ministry also said Jan Dhan accounts do not require a minimum balance and customers are not penalised for a zero balance, and that the Financial Inclusion Index rose from 43.4 in 2017 to 70 in 2026. These state the position claimed by the ministry; they are not freshly announced scheme changes.
Key facts- Most PSBs: waived or reduced minimum-balance non-maintenance charges (ministry statement)
- Statement: 16 October; a policy rebuttal, not a new regulation
- Jan Dhan accounts: no minimum balance or zero-balance penalty (ministry); FI-Index 70 in 2026 vs 43.4 in 2017
Exam takeaway: A ministry rebuttal statement is attributed advocacy, not a regulation; bank-specific charges follow each bank's own schedule.
Quick revision: Finmin: most PSBs waived/reduced minimum-balance charges.
PTI reports of a finance ministry statement (Rediff; The Hindu BusinessLine) original source The Hindu BusinessLine, 17 October 2026Government Schemes
No verified update for this section today.
Credit/NPA & Risk Management
Supreme Court upholds quashing of YES Bank AT-1 bond write-down
Judgment 15 October 2026; bank disclosure 16 October | YES Bank, stock-exchange disclosure of 16 October 2026
The Supreme Court delivered its judgment on 15 October 2026 in proceedings over the write-down of Additional Tier-1 (AT-1) bonds aggregating Rs 8,415 crore, undertaken in March 2020 during the reconstruction of YES Bank. This is a dated 15-16 October development carried in this edition with its dates.
YES Bank's 16 October stock-exchange disclosure states that the Supreme Court upheld the Bombay High Court judgment of 20 January 2023 and dismissed the appeals filed by the Bank, the Reserve Bank of India and the Union of India.
The bank said it respects the judgment, is examining it in detail including all available legal options, and has access to appropriate capital-management levers. The disclosure itself does not quantify any capital action.
Key facts- AT-1 write-down: Rs 8,415 crore, March 2020, YES Bank reconstruction
- Supreme Court judgment: 15 October 2026; upheld Bombay HC judgment of 20 January 2023
- Appeals dismissed: Bank, RBI and Union of India
Exam takeaway: A judgment upholding the quashing of a write-down does not itself order a specific capital issuance; note what the bank did and did not state.
Quick revision: YES AT-1: SC upholds quashing; Rs 8,415 crore.
Dated item: judgment of 15 October and disclosure of 16 October 2026, included because it had not appeared in earlier editions.
YES Bank, stock-exchange disclosure of 16 October 2026 original sourceNational, International & Appointments
Fairfax proposes Kannan as IDBI chairman; Sharma to continue as CEO
16 October 2026 report | Business Standard report of Fairfax analyst call
Business Standard reported on 16 October that Fairfax Financial Holdings has proposed N S Kannan, former MD & CEO of ICICI Prudential Life Insurance and former Executive Director and CFO of ICICI Bank, as IDBI Bank's chairman, subject to RBI approval. Rakesh Sharma will continue as MD & CEO, Prem Watsa said on an analyst call.
The report says Fairfax is preparing to acquire a 60.72% stake in IDBI Bank for Rs 52,878 crore and expects to complete the acquisition as early as the first quarter of 2027, subject to regulatory approvals. This is a reported plan and expectation, not a completed transaction.
Deepak Parekh and Paresh Sukthankar will work with Fairfax as advisers, and C V R Rajendran as an adviser, per the report. Under RBI requirements cited, Fairfax would reduce its IDBI stake to 40% within 10 years and 26% within 15 years.
Key facts- Proposed chairman: N S Kannan, subject to RBI approval (report)
- Rakesh Sharma to continue as MD & CEO (report)
- Reported expectation: completion as early as Q1 2027, subject to approvals
Exam takeaway: Keep earlier guidance in view: stake-sale approval, a named proposed chairman and a completed change of control are three different stages.
Quick revision: IDBI: Kannan proposed chairman, subject to RBI approval.
Business Standard report of Fairfax analyst call original sourceNational, International & Appointments
HDFC Bank Deputy MD Kaizad Bharucha to step down on 31 December
17 October 2026 | CNBC-TV18 report of HDFC Bank stock-exchange filing
HDFC Bank said in a stock-exchange filing on 17 October that Deputy Managing Director Kaizad Bharucha has sought to step down with effect from the close of business hours on 31 December 2026, CNBC-TV18 reported.
The bank's Governance, Nomination and Remuneration Committee (16 October) and board (17 October) accepted the request, which will be forwarded to the RBI for approval. Bharucha joined HDFC Bank in October 1995 and became Deputy Managing Director in April 2023.
The report notes MD & CEO Sashidhar Jagdishan is due to step down at the end of his term on 26 October 2026, and that the bank had submitted two candidate names to the RBI for the top job. The filing does not disclose the candidates' identities.
Key facts- Bharucha exit: effective close of business 31 December 2026
- Board acceptance: 17 October; forwarded to RBI for approval
- Jagdishan term ends: 26 October 2026 (report)
Exam takeaway: A resignation accepted by a board still goes to the regulator; effective dates govern, not meeting dates.
Quick revision: HDFC Bank: Bharucha to exit 31 December.
CNBC-TV18 report of HDFC Bank stock-exchange filing original sourceKnowledge Article
Reading a bank results announcement: PAT, NII, NIM, GNPA, NNPA and PCR
Bank results disclosures of 17 October 2026
Profit after tax (PAT) is the bottom line after all expenses, provisions and tax. Net interest income (NII) is interest earned minus interest paid, and net interest margin (NIM) expresses that income against interest-earning assets. A bank can post higher PAT on lower provisions even when NIM is flat.
Gross NPA ratio is gross non-performing assets as a share of gross advances. Net NPA nets out provisions. Provision coverage ratio (PCR) shows how much of the bad-loan stock is provided for. Punjab & Sind Bank quotes a PCR "with technical write-offs" of 92.48%, which is computed on a different base from a plain PCR.
Capital ratios sit apart from asset-quality ratios. HDFC Bank reports capital adequacy of 18.9% with CET1 of 17.1%, while ICICI Bank reports CET1 of 16.01% and a total ratio of 16.68%. The two banks are not interchangeable on any single number.
Finally, check the basis: HDFC's headline PAT is standalone, ICICI files both standalone and consolidated figures, and growth percentages may use average balances for the quarter rather than end-of-period balances.
Key facts- PAT, NII and NIM measure different things
- GNPA, NNPA and PCR: stock, net stock and provision cover
- Quote each ratio with its bank, basis and date
Bank results disclosures of 17 October 2026 original sourcePractical Banking Case Study
Provision coverage arithmetic on an assumed loan book
Illustrative study, not news. Balances below are assumed; formula usage checked on 18 October 2026.
Assume a bank has gross advances of Rs 50,000 crore. Gross NPAs are Rs 750 crore, provisions held against them Rs 600 crore, and net advances (gross advances minus provisions) therefore Rs 49,400 crore.
Working- GNPA ratio = Rs 750 / Rs 50,000 = 1.50%.
- PCR = Rs 600 / Rs 750 = 80%.
- NNPA = Rs 750 - Rs 600 = Rs 150 crore. NNPA ratio = Rs 150 / Rs 49,400 = about 0.30%.
- Note the denominator change: gross NPA uses gross advances, net NPA uses net advances. Swapping the two understates or overstates the answer.
Exam takeaway: Compute GNPA, PCR and NNPA in sequence, and use the matching advance base for each ratio.
Today's Scheme
Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY)
Department of Financial Services, Ministry of Finance
PMJJBY is a one-year renewable term-life insurance scheme offered through participating banks and post offices. All individual (single or joint) account holders aged 18 to 50 years are entitled to join, and a person with multiple accounts may join through one account only.
Life cover of Rs 2 lakh is payable on the subscriber's death due to any cause. The annual premium is Rs 436 per subscriber, auto-debited from the designated bank or post-office account in one instalment, as per the enrolment consent.
The cover period runs from 1 June to 31 May. Mid-period first-time enrolment pays pro-rata premium: Rs 342 for September-November, Rs 228 for December-February and Rs 114 for March-May enrolment, while renewal always costs the full Rs 436.
For first-time subscribers, risk cover starts from the date of auto-debit, but death other than by accident during the first 30 days (lien period) is not covered. The scheme is distinct from PMSBY, which covers accident death and disability for a different premium.
Key facts- Eligibility: age 18-50, one participating bank/post-office account
- Cover: Rs 2 lakh on death due to any cause; premium Rs 436/year auto-debit
- Policy year: 1 June to 31 May; 30-day lien for first-time non-accident claims
Exam takeaway: Do not mix PMJJBY (life cover, Rs 2 lakh, Rs 436) with PMSBY (accident cover, Rs 20) or APY (pension). Check the lien period and single-account rule.
Department of Financial Services, Ministry of Finance original sourceBank Promotion Exam Corner
Policy rates unchanged from the 17 October edition: repo 5.50%, SDF 5.25%, MSF/Bank Rate 5.75%, effective 7 October; CRR 3%; SLR 18%.
Q2FY27 net profit: HDFC Bank Rs 195 billion, ICICI Bank Rs 148.43 billion (up 20.1%), Axis Bank Rs 7,003 crore (up 38%), Punjab & Sind Bank Rs 412 crore (up 39.66%). Units and bases differ by bank.
YES Bank AT-1: Supreme Court judgment of 15 October upheld the Bombay High Court quashing of the Rs 8,415 crore write-down; bank disclosed it on 16 October.
IDBI Bank: N S Kannan is a proposed chairman subject to RBI approval; the Fairfax acquisition is a reported plan awaiting regulatory approvals, not a completed transaction.
Daily MCQ Challenge
1. Which bank reported the highest Q2FY27 net profit among the four in this edition?
A. Axis Bank
B. ICICI Bank
C. HDFC Bank
D. Punjab & Sind Bank
Answer: C. HDFC Bank's standalone PAT was Rs 195 billion (about Rs 19,500 crore), above ICICI's Rs 148.43 billion, Axis's Rs 7,003 crore and P&S Bank's Rs 412 crore.
2. The Supreme Court judgment on YES Bank's AT-1 bonds was delivered on:
A. 20 January 2023
B. 15 October 2026
C. 16 October 2026
D. March 2020
Answer: B. 15 October 2026 is the judgment date; 20 January 2023 is the Bombay HC judgment it upheld, and 16 October is the bank's disclosure date.
3. Under PMJJBY, the annual premium and life cover are:
A. Rs 20 and Rs 2 lakh
B. Rs 436 and Rs 2 lakh
C. Rs 436 and Rs 4 lakh
D. Rs 342 and Rs 1 lakh
Answer: B. PMJJBY charges Rs 436 per year for Rs 2 lakh cover on death due to any cause; the Rs 20 premium belongs to PMSBY.
4. Indian Bank aims to complete its Rs 3,500 crore expected-credit-loss provisioning by:
A. September 2026
B. December 2026
C. March 2027
D. March 2028
Answer: C. The MD & CEO told NDTV Profit the bank aims to finish the Rs 3,500 crore ECL provisioning by March 2027.
5. Among the four results in this edition, which bank reported a net interest margin of 2.77%?
A. Punjab & Sind Bank
B. Axis Bank
C. HDFC Bank
D. ICICI Bank
Answer: A. Punjab & Sind Bank reported NIM of 2.77%, up 17 basis points; the others reported 3.36% (Axis) and 3.16% (HDFC).
Revision: recent days
15 October 2026: Earlier edition: IDBI 60.72% strategic-sale approval was not transaction completion.
16 October 2026: Earlier edition: September PLFS unemployment 5.0% for persons aged 15+; FERR user-contract threshold strictly above USD 2 million, subject to all scope conditions.
17 October 2026: Earlier edition: RBL amalgamation approval of 16 October is not its 1 December effective date; the Rs 14,614 SGB price is tranche-specific.
Sources and publication information
Four results stories use official bank documents (exchange filings, presentations and press releases dated 17 October 2026). The YES Bank item is a dated 15-16 October development not previously covered. The IDBI and HDFC leadership items are attributed to Business Standard and CNBC-TV18 reports of an analyst call and an exchange filing; proposals and reported expectations are not completed events. The finance-ministry minimum-balance statement of 16 October is reported via PTI (Rediff, 16 October; The Hindu BusinessLine, 17 October). No new RBI press release appeared after the 16 October releases used in the 17 October edition. Public sources are linked by name, not printed as raw URLs. All questions are original practice.